
Key Takeaways
- Property taxes and insurance are recurring ownership expenses, but their amounts depend heavily on location and property characteristics.
- Maintenance reserves are important because major repairs can arrive without warning and may require substantial savings.
- Condominium owners and detached-home owners face different expense structures, so comparing their budgets requires more than looking at monthly fees.
How Much Does It Really Cost to Own a Home in Canada?
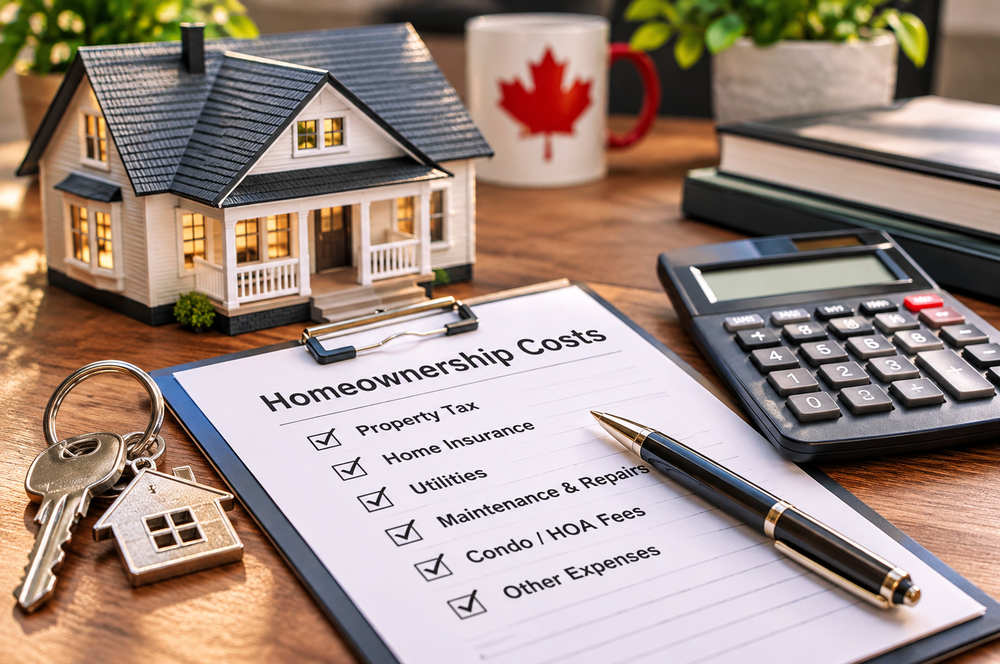
Canadian property ownership costs go well beyond the mortgage payment. Homeowners must also budget for property taxes, insurance, electricity, heating, water, maintenance and occasional repairs. Condominium owners may have additional monthly fees, while detached-home owners usually handle more exterior maintenance themselves.
The actual annual amount depends on the property's location, age, size, condition and type. A newer condominium in one city may have a very different expense structure from an older detached house in another. There is no single annual ownership figure that applies to every Canadian household.
Which Annual Expenses Should Homeowners Include?
Property taxes: Municipal governments collect property taxes to help fund local services. The amount depends on the property's assessed value and the municipality's tax rates. Homeowners should check their latest tax bill instead of relying on a national average.
Home insurance: Insurance protects against covered property damage and certain liabilities. Premiums vary according to location, rebuilding costs, property age, coverage and claims history. Homeowners should review exclusions and deductibles rather than choosing a policy based on price alone.
Utilities: Electricity, natural gas, heating oil, water and waste services can create substantial recurring expenses. Weather, household size, insulation, appliance efficiency and personal consumption all influence the final bill.
Internet and communication: Internet, telephone and television services are additional household expenses. Although they are not property taxes or structural maintenance costs, they should still appear in the monthly household budget.
How Much Should Homeowners Budget for Maintenance and Repairs?
Maintenance is one of the easiest expenses to underestimate because homeowners do not necessarily pay the same amount every month.
Routine work may include furnace servicing, gutter cleaning, plumbing checks, lawn care, snow removal and minor electrical repairs. Larger expenses can include roof replacement, window repairs, water damage, heating equipment replacement and exterior renovations.
A homeowner should maintain a separate repair reserve instead of waiting for something to break. The appropriate amount depends on the property's age, condition, construction type and existing maintenance history.
For example, an older property with an aging roof and heating system deserves a larger repair allowance than a recently built home with newer equipment. A professional inspection can help identify upcoming expenses before they become emergencies.
Do Condominium Owners Have Different Ownership Costs?
Yes. Condominium owners usually pay monthly maintenance fees to the condominium corporation. These fees help cover shared expenses such as building insurance, common-area cleaning, elevators, landscaping and certain maintenance responsibilities.
The amount depends on the building, unit size, services and financial requirements of the condominium corporation.
However, a lower monthly fee does not always mean a cheaper property to own. Buyers should review the building's reserve fund, financial statements, maintenance history and planned repairs. Special assessments can create additional costs when available funds are insufficient for certain expenses.
Detached homeowners generally have more direct responsibility for roofs, driveways, gardens, exterior walls and other private property features.
What Unexpected Expenses Can Affect a Homeowner's Budget?
Some ownership expenses are difficult to predict precisely. A damaged water heater, leaking roof, plumbing failure or appliance breakdown can require immediate attention.
Homeowners may also face costs associated with:
- Pest removal and property protection.
- Tree trimming and landscaping.
- Snow removal and driveway maintenance.
- Security systems and equipment servicing.
- Appliance replacement.
- Emergency plumbing and electrical work.
These expenses are not necessarily annual bills, but ignoring them can create financial pressure when they occur. Keeping an emergency reserve separate from regular household savings provides greater flexibility.
How Can You Calculate Your Annual Property Ownership Costs?
Homeowners can estimate their annual expenses using a straightforward formula: Annual ownership costs = Property taxes + Insurance + Utilities + Maintenance + Condo fees (if applicable) + Other recurring property expenses.
Consider a hypothetical homeowner with the following annual budget:
- Property taxes: $4,000
- Home insurance: $1,800
- Electricity and heating: $3,000
- Water and waste: $900
- Maintenance reserve: $3,000
- Internet and other services: $1,200
Illustrative annual total: $13,900.
This equals approximately $1,158 per month, excluding the mortgage payment. These figures are invented budgeting assumptions, not Canadian average costs or market estimates. A homeowner should replace them with actual municipal bills, insurance quotations and utility statements.
TwikUp's Perspective
A property can appear affordable during the buying process but become difficult to manage when several expenses arrive together. Homeowners should evaluate the complete cost of ownership before committing to a purchase, not simply ask whether they can qualify for the mortgage.
The most useful approach is to build a twelve-month budget, review actual bills and maintain separate savings for repairs and emergencies. Buyers comparing locations should also examine local property taxes, building condition and municipal services before deciding.
For a broader understanding of regional housing conditions, readers can explore our Ontario housing market forecast for 2027 and Alberta real estate forecast comparing Calgary and Edmonton. A property's purchase price is only one part of the financial commitment. Its long-term operating costs deserve equal attention.
Disclaimer
This article is for educational and informational purposes only. Ownership expenses vary by property, municipality, province and household circumstances. The illustrative budget is not a national cost estimate. Readers should obtain current quotations and review local charges before making property decisions.